The Long End of the Curve
Big moves in the stock market are often anticipated by bonds. Earlier this week, yields on the 10-Year U.S. Treasury note moved above 5%, reaching levels not seen since 2007.

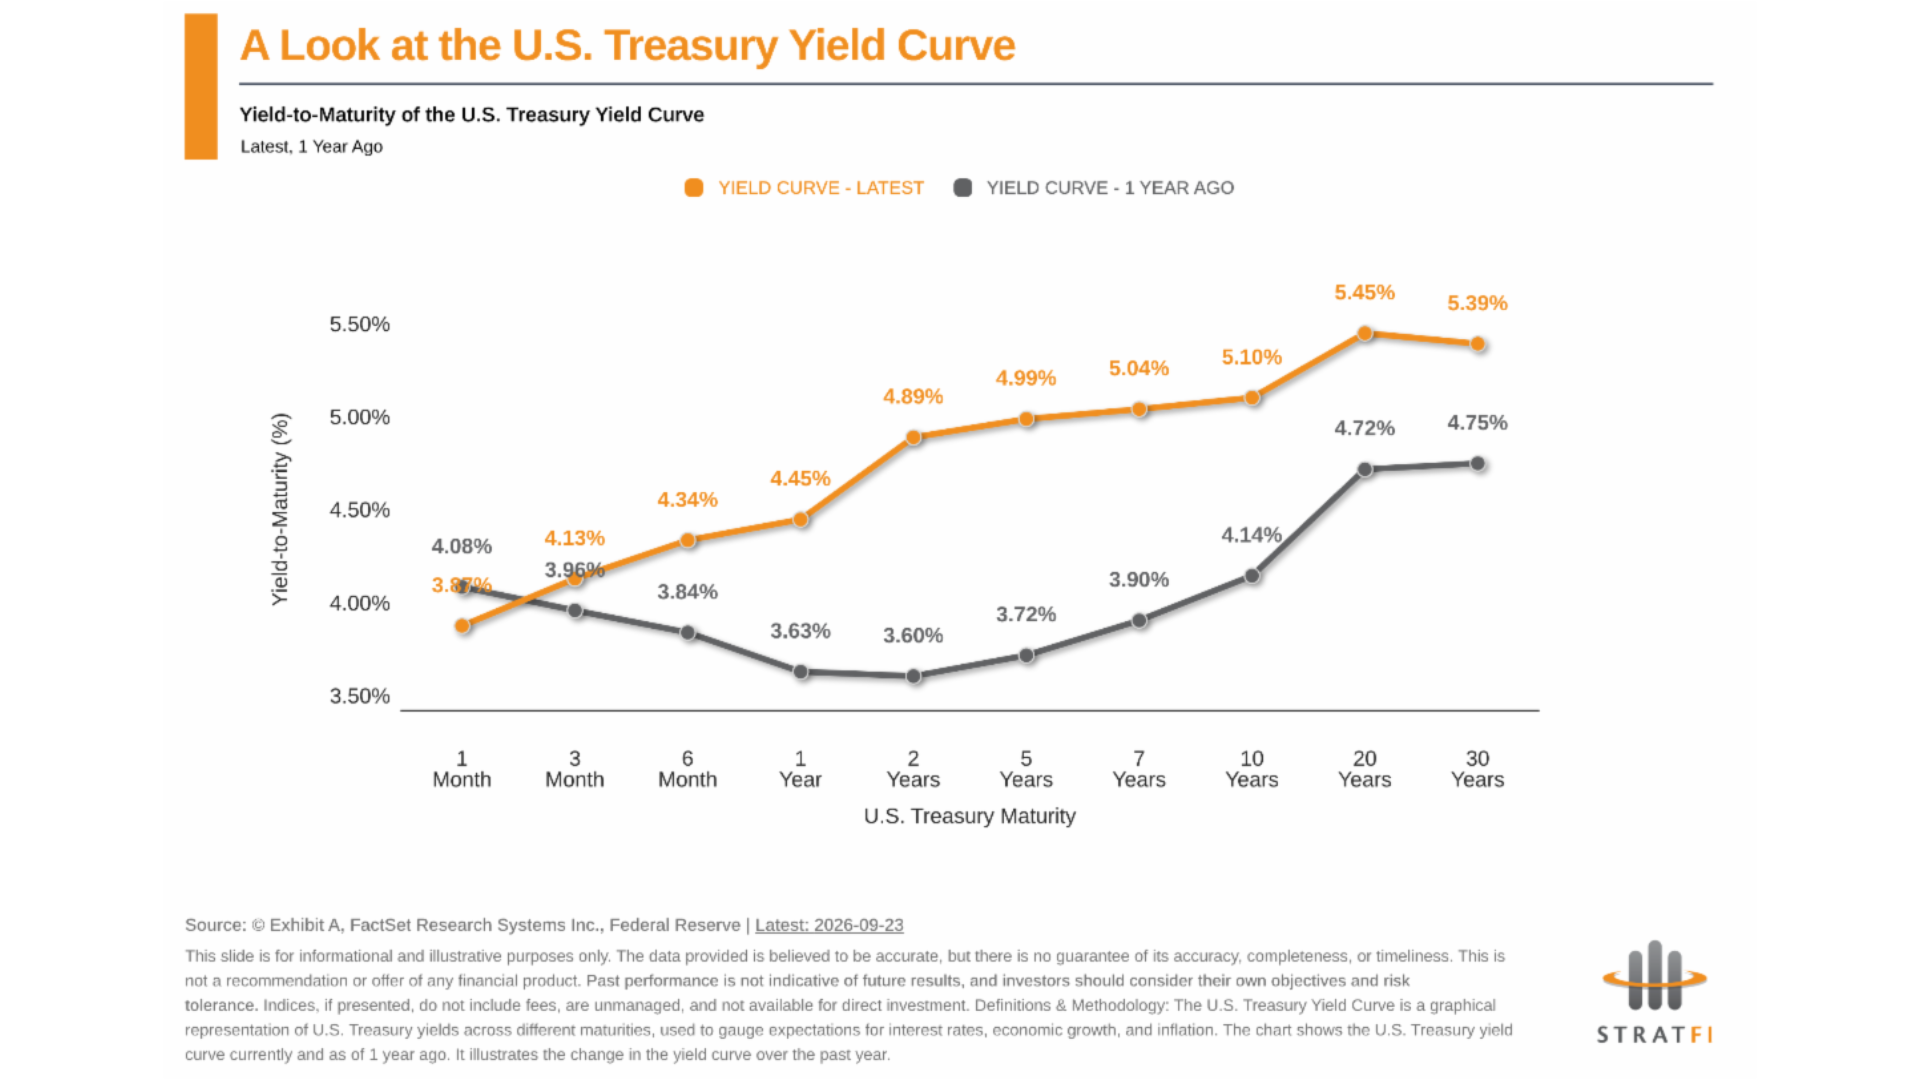
Big moves in the stock market are often anticipated by bonds.
Earlier this week, yields on the 10-Year U.S. Treasury note moved above 5%, reaching levels not seen since 2007.
Long-term rates are rising for several reasons.
- Economic growth remains surprisingly strong.
- Higher oil prices add inflationary pressure.
- Rising U.S. debt means investors must absorb an enormous supply of new bonds.
So, investors are demanding higher yields on longer-term bonds to compensate for inflation and fiscal uncertainty.
Why should anyone care?
The implications extend far beyond bonds.
- The housing market is still a big part of the economy. Higher long-term bond yields usually mean higher rates on home mortgages. 30-year mortgages are now above 7%.
- Refinancing becomes more expensive for businesses and households with a lot of debt.
- Existing long-term bonds fall in value as newly issued bonds offer more attractive yields.
- Stock valuations change, too. Higher interest rates make investors impatient for profits to happen sooner rather than later.
Interest rates and bond yields have been kept artificially low since the financial crisis of 2008-2011. For more than a decade afterwards, investors became accustomed to a "new normal" of slower growth, low inflation and exceptionally cheap money. This has led to higher housing prices and higher stock prices.
Everyone is happy, right?
… at least until housing becomes unaffordable and parts of the stock market start looking frothy.
Rates could move higher and for longer. Higher interest rates are not automatically bad. They simply change the price of money. And when the price of money changes, almost everything else eventually gets repriced too.
We’re just going back to interest rates that were typical until about 20 years ago.
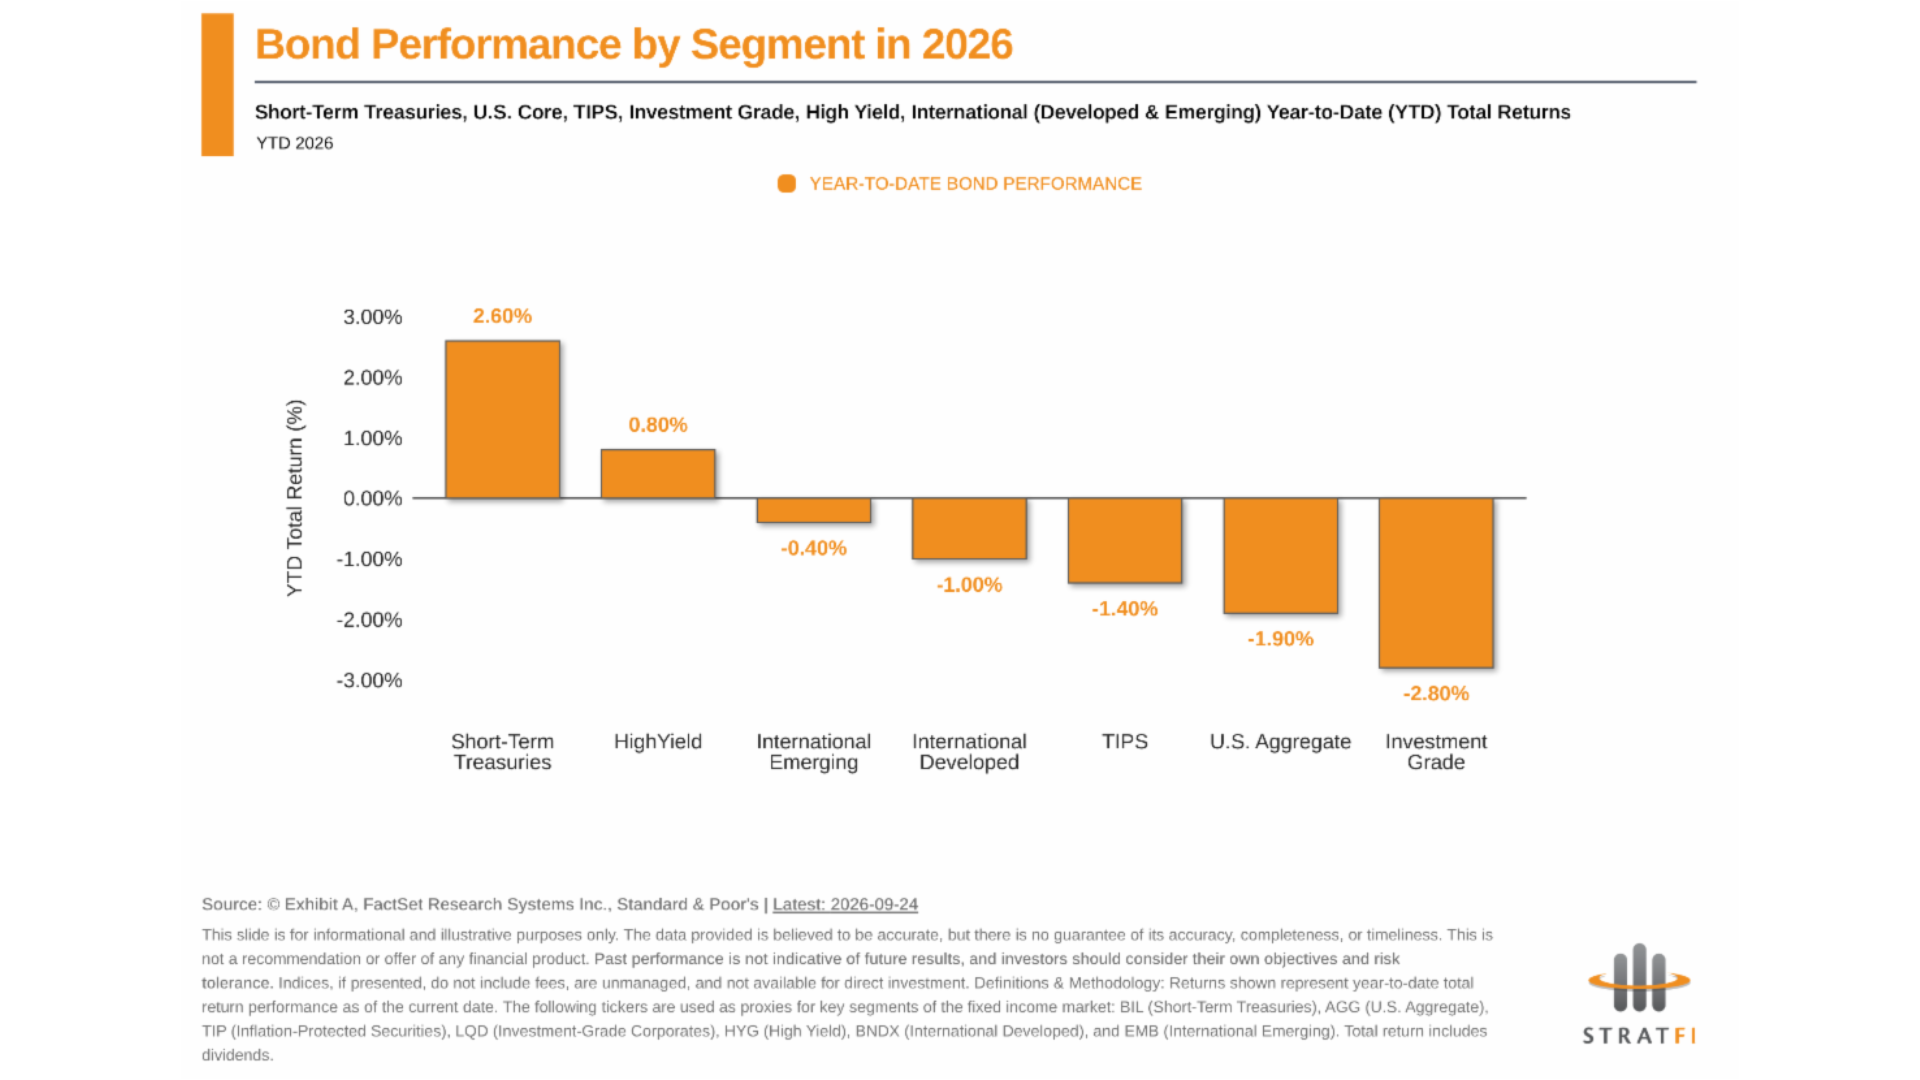
Our clients have strategically low exposure to bonds simply because we didn’t feel they were a good deal. For the few bond funds we recommend, we’ve been focused on short-term maturities. By managing for duration risk, we've avoided most of the recent trouble in the bond markets.
In a rising rate environment, short-term bonds tend to do much better than long-term bonds. It’s the part of the yield curve that you want.
We’ve found fixed-income alternatives in some interesting places, including closed-end funds, infrastructure, and options strategies.
It doesn’t make sense to use a traditional rulebook when the old way of thinking is broken.
Feel free to reach out if you have questions on how we are positioning for the next “new normal.”
Copyright ©️ 2026. All Rights Reserved.
About the author
Disclosure
Information contained herein is for educational purposes only and is not to be considered a recommendation to buy or sell any security or investment advice. Securities listed herein are for illustrative purposes only and are not to be considered a recommendation. The author and StratFI clients may hold positions in securities mentioned.
Do you want monthly
Foresight straight to your inbox?
Straightforward commentary, strategic perspectives, and no noise — just one email a month to help you think smarter about your financial future.
Related articles
Explore timely insights and thoughtful perspectives from James Lee and StratFI. Each article is designed to help you cut through the noise, understand the bigger picture, and invest with confidence.

Straightforward commentary, strategic perspectives, and no noise, just one email a month to help you think smarter about your financial future.